
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
International company formation from start to finish: we pick the country that fits your clients and taxes, register the company, prepare it for the bank and handle the reporting, including CFC reports in Ukraine for Ukrainian tax residents.
Since 2012 · 50+ jurisdictions · company, bank account, accounting and CFC in one team · free 10-minute call
In brief
Eleven countries where our clients most often set up a company; each has a detailed page with taxes, timelines and documents.
In total we work in 50+ jurisdictions. If you are looking at Europe as a whole, see our catalogue on company formation in Europe, and a holding structure is best started with a free consultation on international structuring.
Six situations clients most often bring to us, and the route we usually suggest.
We look at your contracts, payment currency and where the owner lives. Most often this is a UK LTD, a Polish sp. z o.o. or a US LLC.
Example. A development team from Lviv works with clients in Germany as Ukrainian sole proprietors. In this situation we register an EU company, open a euro account and set up the Ukrainian CFC report.
Discuss this case →We register an LLC, obtain an EIN and prepare the package for the payment provider. Form 5472 and state taxes go into the calendar from day one.
Example. A home goods store enters Amazon US: we open a Wyoming LLC and handle the bookkeeping and IRS filing every year.
Discuss this case →We link the choice of country to the immigration route: in the UAE the company gives an investor visa, in the EU we check residence permit conditions for business owners.
Example. An entrepreneur moves to Dubai with family: a free zone company, investor visa, Emirates ID and an account with a local bank.
Discuss this case →You need a company with an EU VAT number and a clear supply chain. We choose the country around the warehouse, buyers and logistics, usually Poland, Romania or Bulgaria.
Example. A furniture manufacturer opens a company in Poland, registers it for VAT and sells to EU buyers from a warehouse near the border.
Discuss this case →We review the fund's requirements and build a structure for the round and the team's options: a Delaware C-Corp for US funds, an EU or UK holding for European investors.
Example. Before a seed round, a SaaS team moves its IP and shares into a Delaware corporation and keeps the Ukrainian company as a service entity.
Discuss this case →We check the register, tax office and reporting, close the gaps and take the company into ongoing support together with the Ukrainian CFC filings.
Example. A UK LTD has an overdue confirmation statement and the director has not completed identity verification: we file the statement, complete verification and put deadlines in the calendar.
Discuss this case →International company formation covers the whole path from choosing a country to the first filed reports: you get a working company with tax numbers, prepared for the bank, and a calendar of obligations in two countries.

When the business needs contracts, a licence or corporate changes after registration, we bring in legal support for international business. Licences are obtained through partners, and we remain responsible to you.
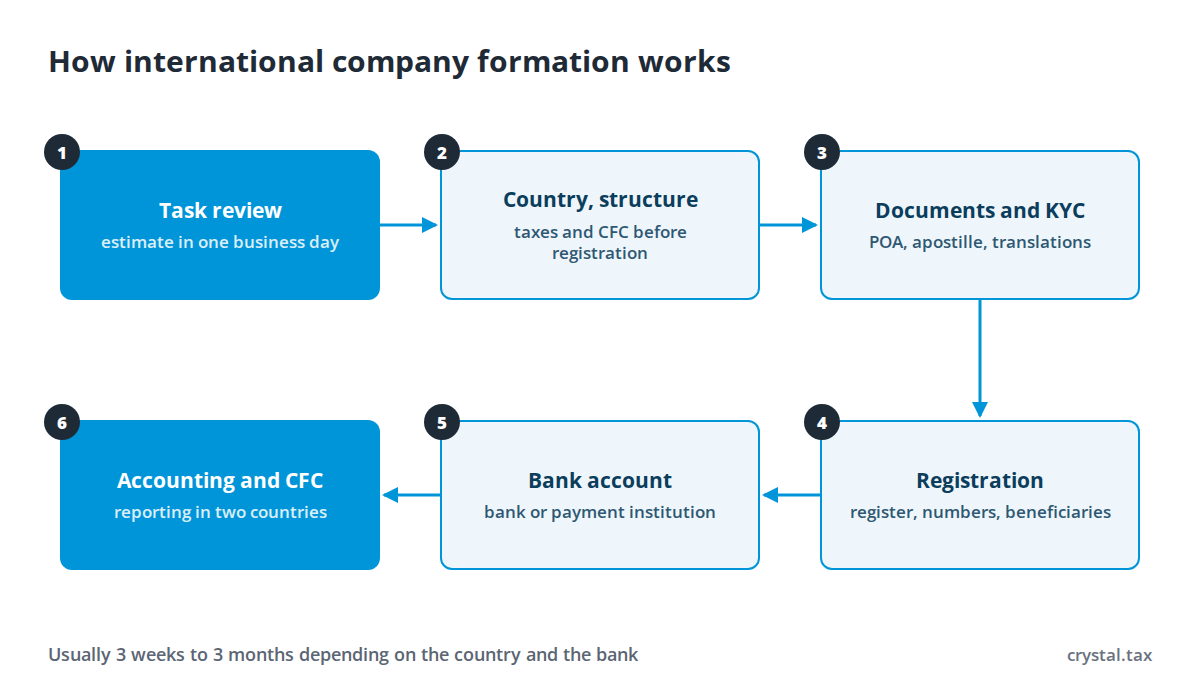
Usually, in our experience, registering a company abroad takes 1 to 6 weeks, and the full launch with a bank account and tax numbers takes 3 weeks to 3 months. Timing depends on the case, its details, the authorities and force majeure.
| Country | Company registration | With bank account and tax numbers |
|---|---|---|
| United Kingdom | 1–2 weeks including verification and address | 3–8 weeks |
| USA | 2–5 weeks including EIN | account after the EIN, timing set by the bank or fintech provider |
| UAE | licence in 1–3 weeks | 1.5–3 months with visa, Emirates ID and account |
| Poland | 3–5 weeks to entry in the KRS | 1.5–3 months with VAT and account |
| Hungary | 2–3 weeks | 3–6 weeks |
| Romania | 1–2 weeks | 3–6 weeks with a Romanian account |
| Bulgaria | 2–4 weeks after documents are received | another 2–8 weeks for account and VAT |
| Italy | 3–6 weeks with partita IVA | 6–12 weeks |
| Canada | 1–2 weeks with business number | 4–10 weeks |
| Panama | 1–3 weeks after founder checks | 1–3 months |
| Kenya | 2–4 weeks with KRA PIN | 1–3 months |
Official register timelines cover only the review of a complete application. They exclude powers of attorney, apostille and translations, director verification, bank checks and answers to compliance queries. If you need the company by a certain date, for example to sign a contract, tell us at the start: we will choose the country and the order of steps around that date.
We quote the cost of international company formation per case: it depends on the country, the structure and the scope of support after registration.
We give an estimate within one business day after a short description of the task. We work under a contract that fixes the scope of work and the timeline for each stage.
Registering abroad involves dozens of details at the register, the bank and the tax office, and clients trust us with them for five reasons.
For fourteen years we have been registering companies, opening accounts and handling tax and immigration matters in 50+ jurisdictions. We know what registrars, banks and tax offices require from our own cases.
We handle the correspondence with the register, tax office, bank and immigration service ourselves and answer their queries. From you we need documents and decisions.
We resolve comments from the registrar, tax office, bank or immigration service at no extra charge until the company is up and running.
The company, bank account, accounting, taxes including the Ukrainian CFC rules, and immigration are handled by Crystal Tax lawyers and accountants together with local partners. You do not have to look for separate contractors.
Scope of work, timelines and confidentiality are set out in the contract. We disclose information about you and the company only to the extent the procedure requires.
The work runs in six stages: we need documents and decisions from you, and we do the rest.
To register a company abroad, each owner and director provides a passport, proof of address and information on the source of funds, and the future company needs a business description.
Some countries have their own requirements: a codice fiscale for founders in Italy, a KRA PIN for directors in Kenya, identity verification with Companies House in the UK. We arrange translations, apostille and certification ourselves, and give the exact list for the country and bank after reviewing the task.
Most often a bank refuses when the business model is unclear, there is no link to the country of registration, or the source of funds is not proven. Sanctions and PEP checks, inconsistencies between documents and an unclear tax residence of the owner add risk. We prepare the business profile, contracts and source-of-funds package before applying and match the owners' details across all documents. The decision to open an account is made by the bank.
The table helps narrow the choice to two or three countries; we make the final decision after calculating taxes in the company's country and in Ukraine. Rates as of September 2026.
| Country and form | Corporate income tax, 2026 | Remote registration | Bank and substance | Reporting |
|---|---|---|---|---|
| United Kingdom, LTD | 19 percent on profit up to GBP 50,000, 25 percent above GBP 250,000, marginal relief in between | Yes; directors and PSCs complete Companies House identity verification | A UK address is required; traditional banks often expect a link between the business and the UK | Confirmation statement, annual accounts, CT600 return |
| USA, LLC or C-Corp | A single-member LLC is transparent for federal tax by default; C-Corp pays 21 percent plus state tax | Yes, including the EIN via Form SS-4 | Traditional banks often ask for a visit; fintech providers work remotely | Foreign-owned single-member LLC: Form 5472 with a pro forma 1120, USD 25,000 penalty for not filing; state report or tax |
| UAE, free zone | 0 up to AED 375,000, 9 percent above; 0 on qualifying free zone income if conditions are met | Registration is remote in many zones; visa and Emirates ID require a visit | The 0 rate requires substance in the free zone and audited IFRS accounts; the bank usually expects a visa and a meeting | Corporate tax return within 9 months after year end, licence renewal |
| Poland, sp. z o.o. | 19 percent; 9 percent for small taxpayers with revenue up to EUR 2 million or in the first year of activity, except capital gains | Yes, by power of attorney before a notary or through S24 | For VAT the tax office may ask for a lease agreement and evidence of activity | JPK_V7 monthly, CIT-8, annual financial statements to the KRS |
| Hungary, Kft | 9 percent plus local business tax up to 2 percent; KIVA regime for small companies | Yes, a lawyer files with the court electronically; share capital HUF 3 million | The law allows bank identification by video call; the decision rests with the bank | Annual report and tax return by 31 May |
| Romania, SRL | 1 percent of revenue for revenue up to EUR 100,000 and at least one employee, otherwise 16 percent | Yes, with an electronic signature or through a representative | A Romanian account is mandatory; a new company opens it within 60 business days | Annual financial statements by 31 May, VAT 21 percent |
| Bulgaria, EOOD | 10 percent, dividends 5 percent | Yes, signing before a notary in your own country with an apostille | The bank often asks for the signatory to visit in person | Tax return by 30 June, financial statements to the register by 30 September |
| Italy, SRL | IRES 24 percent plus IRAP, standard rate 3.9 percent | Yes, by power of attorney or by video call with a notary | Founders need a codice fiscale and the company a PEC address; the bank checks owners in detail | Financial statements to the register in XBRL, Redditi SC and IRAP returns, e-invoicing |
| Canada, corporation | Under non-resident control: 15 percent federal, 26.5 percent combined in Ontario | Yes, online applications | A federal corporation needs at least 25 percent resident Canadian directors, Ontario has no such rule; banks often ask the director to visit | T2 return within 6 months after year end, annual return, ISC register |
| Panama, S.A. | 25 percent on Panama-source income only; from 2027, 15 percent on foreign passive income of groups without substance | Yes, through a resident agent | On the EU list of non-cooperative jurisdictions, so banks check more strictly; a Panamanian bank more often expects a visit | Accounting records to the agent by 30 April |
| Kenya, private company | 30 percent | Yes; directors need a KRA PIN and there must be a contact person in Kenya | The bank may ask to meet the director | Monthly returns in iTax, including nil returns, annual filings with the BRS and KRA |
Estonia, Cyprus, Singapore and other countries among our 50+ jurisdictions are reviewed on request; European options are collected on the page about company formation in Europe.
For a Ukrainian tax resident, any foreign company they control is a CFC (controlled foreign company): its profit is reported in Ukraine, and whether tax is due on it is decided by Article 39-2 of the Tax Code of Ukraine.
Under clause 39-2.4.1, CFC profit is not taxed in Ukraine if two conditions are met at the same time:
Separately, under clause 39-2.4.2.1, profit is exempt if the total income of all CFCs of one owner does not exceed the equivalent of EUR 2 million at the end of the reporting period. The rates in Hungary, Bulgaria and the UAE and the Polish reduced 9 percent are below the 13 percent threshold, so for such companies the exemption is usually based on the share of passive income or on the EUR 2 million limit. Ukraine has no double tax treaty with Panama, so for a Panamanian company we first check the exemptions in clause 39-2.4.2.
Ukraine signed the multilateral agreement on automatic exchange of financial account information under the CRS standard in 2022, with the first exchange planned for September 2024; the UAE, Panama and Kenya have also signed it. So we build the structure to be transparent from the start: information on foreign accounts may reach the State Tax Service of Ukraine. We prepare the CFC report together with the company's reporting: CFC: report and structure.
One operating company is enough while the business has one main market, one or two owners and no outside investors; a holding is needed when there are several companies, intellectual property, partners or an investment round. For a product startup, the country, founder equity and IP are covered on our page where to incorporate a startup.
A freelancer, agency or online store usually needs just one company in the country of its clients or payment provider. Accounting is simpler, the bank sees a clear structure, and one CFC report is filed in Ukraine.
A holding keeps shares and intellectual property separate from operating risks, collects dividends in one place and lets partners come in at its level. Tax on dividends inside the structure depends on the double tax treaties between the countries. Under the CFC rules dividends count as passive income, so we check the exemption conditions for the holding before registration.
US venture funds usually invest in a Delaware C-Corp: it has share classes, well-developed corporate law and standard round documents. An LLC suits an owner-operated business, and funds rarely invest in one. Converting an LLC into a C-Corp is possible, but it takes a separate procedure and tax analysis, so we choose the form from the start to match the funding plan.
The option pool is usually created in the parent company where investors come in. For employees in Ukraine we calculate the taxes on receiving shares in advance.
We do not use nominee directors or shareholders in our structures: beneficial ownership registers and banks see the real owner, and the structure must hold up to that.
Describe your business, your clients and where the owners live, and we will reply within one business day with one or two suitable countries. You can start with a free 10-minute call.
Tax Code of Ukraine, Article 39-2 and paragraph 72 of subsection 10, section XX (version of 17.09.2026); GOV.UK: Corporation Tax rates and reliefs; GOV.UK: When you need to verify your identity for Companies House; IRS: Instructions for Form 5472; UAE Ministry of Finance: Corporate Tax; CRA: Corporation tax rates; PwC Worldwide Tax Summaries: Poland, corporate income; PwC Worldwide Tax Summaries: Romania, corporate income; PwC Worldwide Tax Summaries: Italy, corporate income; OECD: CRS MCAA signatories and intended first exchange dates. Checked: 27.09.2026.
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
“Crystal Tax provided invaluable assistance in setting up our company in the United Arab Emirates…”
Yevelina K.2 years ago · Google Maps
“Opening a bank account abroad sounded scary at first, but Crystal Tax made it super easy. They knew exactly which banks to approach, what paperwork was needed…”
Sergei M.a year ago · Google Maps
“As a fast-growing startup, we needed clear, actionable tax advice — and Crystal Tax delivered exactly that. No jargon, no fluff.”
Inna M.a year ago · Google Maps
Briefly describe your task: the country, the business activity and the timing. That is enough for us to propose a solution and the order of work.
We reply within one business day.
Or message us
 Telegram
 WhatsApp
How we work
In the first consultation we review your task and name suitable structure and country options.
Before work starts we fix the scope, stages and estimated timing of each step.
One responsible specialist runs your project. We reply within one business day via Telegram, WhatsApp or email.
Most procedures run remotely. Where the law requires an in-person visit, we plan it in advance.