
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
A trust fund is a trust: a legal arrangement in which the settlor transfers assets to a trustee, and the trustee holds and manages them under a trust deed for the benefit of the beneficiaries. In everyday speech, a trust fund means both the trust itself and the pool of assets it holds. The closest alternative is a private, or family, foundation: it serves the same purposes, but it is a legal entity in its own right, with its own charter and council.
A classic trust fund cannot be set up under Ukrainian law: the Civil Code of Ukraine recognises an asset management agreement (chapter 70, art. 1029) and fiduciary ownership as security for a loan or credit (art. 597-1 et seq.), and it has no separate trust institution of the common law kind. For this reason, owners from Ukraine set up trusts and foundations under the law of another country. The Tax Code of Ukraine expressly lists trusts and foundations among foreign entities without legal personality and may treat such an entity as a controlled foreign company (Tax Code of Ukraine, subpara. 39-2.1.1).
Trust registration and trust fund setup, turnkey: we choose the country and the form, find a licensed trustee, prepare the documents, transfer the assets and handle your Ukrainian CFC reporting.
Since 2012 · 50+ jurisdictions · trusts and private foundations with licensed partners · Ukrainian CFC rules and taxes in one team
In brief
Six situations in which clients come to us for a trust or foundation, and the route we usually suggest.
We build a trust or foundation with clear payment rules by age and life events, appoint the trustee and protector and draft the letter of wishes. A trust fund for a child is set up the same way: the assets are managed professionally until the child comes of age and beyond.
Example. An entrepreneur transfers an investment portfolio and a company stake into a discretionary trust; the children receive payments for education, and the rest after age 25 at the trustee's discretion.
Discuss this case →We move part of the savings into a trust early, while the business faces no claims or disputes, and document the source of funds. Courts can challenge a transfer of assets made to escape creditors, so we do it in good time and within the law.
Example. The owner of a manufacturing company transfers savings from previous years into a trust and gets separate accounting: the business on one side, family capital on the other.
Discuss this case →We place a trust or foundation above a holding company so that management keeps running through a change of generation or the owner's illness. We handle the Ukrainian notices and CFC reports ourselves.
Example. Two co-owners transfer the holding's shares into a foundation with a council, where each family has fixed rights to income and votes.
Discuss this case →We choose the trust law and the bank so that the tax rules of all the beneficiaries' countries of residence fit together. This often goes together with business relocation and a change of residence.
Example. The parents stay in Ukraine, the daughter lives in Poland, the son in Canada: a trust under English law with an account at a bank that works with all three.
Discuss this case →For families with a civil law mindset, we offer private foundations with a council, a charter and by-laws. The classic option is a family foundation in Liechtenstein.
Example. A family sets up a foundation with a council of a licensed local director and a family member and fixes the payment rules in the by-laws.
Discuss this case →We prepare a charitable trust or foundation with a purpose that meets local charity rules. A charitable CFC that does not distribute income to its founders is exempt from tax on CFC profit in Ukraine under subpara. 39-2.4.2.3 of the Tax Code of Ukraine.
Example. A family opens a foundation for student scholarships and funds it from its holding's dividends.
Discuss this case →We handle trust and private foundation registration in countries whose law and registers banks understand, and where trust services are provided by licensed companies.
We choose the country around the family's goals: where the beneficiaries live, which assets go into the trust, which bank will hold them and who will act as trustee. In every country below, the trustee or the foundation council is a licensed local partner or a person required by local law; we find them, agree the terms and run the project.
Form: Express trust under a trust deed
Legal basis: Common law of trusts, Trustee Act 2000
Register and who sees the data: HMRC Trust Registration Service: UK express trusts, except those excluded under Schedule 3A, trusts with UK tax liabilities, and non-UK express trusts that hold UK land or have a UK-resident trustee entering into a business relationship there. For land acquired before 6 October 2020 and held by the trust on 30 June 2026, the registration deadline is 1 September 2027. Third parties receive data on request where they show a legitimate interest linked to a money laundering or terrorist financing investigation, or where the trust owns more than half of a company outside the UK and the EEA
When it fits: The family lives in several countries and needs a law that every bank understands and courts with long practice
Form: International trust: the settlor and beneficiaries are not Cyprus residents, at least one trustee is a resident
Legal basis: Cyprus International Trusts Law 69(I)/1992, as amended by 20(I)/2012, 98(I)/2013 and 240(I)/2025
Register and who sees the data: CyTBOR, the register of beneficial owners of trusts, kept by the Cyprus Securities and Exchange Commission (CySEC) under art. 61C of anti-money laundering law 188(I)/2007
When it fits: A trust under the law of an EU country is needed, assets or a holding are in Europe
Form: Private foundation (Stiftung) and trust (Treuhänderschaft)
Legal basis: Personen- und Gesellschaftsrecht (PGR) of 1926: art. 552 on foundations, art. 897 et seq. on trusts
Register and who sees the data: A foundation that is not entered in the commercial register files a notice of formation with the Amt für Justiz within 30 days; a local lawyer or Treuhänder confirms the accuracy of the data. Beneficial owners are recorded in the register under the VwbPG of 2020
When it fits: The family thinks in civil law terms and wants a foundation with its own legal personality for generations
Form: Trust with a licensed trust company
Legal basis: Trust Companies Act 2005, trust business licence issued by MAS
Register and who sees the data: The trust company is supervised by MAS; the regulator and the bank receive the beneficiary data
When it fits: Assets, accounts and investments in Asia
Trusts and foundations in the Emirates are covered on a separate page: trusts in the UAE. We consider other countries on request if they have a licensed trustee and practice that banks understand.
The tax obligations of a settlor and beneficiaries who are Ukrainian residents remain in place when assets move into a foreign trust or foundation: the Tax Code treats trusts and foundations as foreign entities without legal personality that may be treated as CFCs (Tax Code of Ukraine, subpara. 39-2.1.1). That is why we plan the Ukrainian side at the start, before the trust deed is signed.
Ukraine takes part in the CRS automatic exchange of financial account information; according to the OECD list, its first exchange took place in September 2024. Data on the trust's accounts and its beneficiaries enters this exchange through banks and tax authorities. Our accountants prepare the notices, reports and returns; see the page on CFC reporting.
A trust fund gives confidentiality from outsiders and full transparency for banks and tax authorities. Beneficial ownership registers exist in the UK (TRS at HMRC), in Cyprus (CyTBOR at CySEC) and in Liechtenstein (the register under the VwbPG). The bank that holds the trust's account reports data under CRS to its tax authority, which passes it on to the beneficiary's country of residence. According to the OECD list, the first exchanges took place in September 2017 for the UK, Cyprus and Liechtenstein, in September 2018 for Singapore and in September 2024 for Ukraine.
Access by outsiders to these registers is limited. In its judgment of 22 November 2022 in joined cases C-37/20 and C-601/20, the Court of Justice of the EU declared invalid the provision of the anti-money laundering directive that made information on the beneficial owners of companies accessible to any member of the public in all cases. Third parties get access to the HMRC register only on request with a legitimate interest, or where the trust controls a company outside the UK and the EEA.
We build only structures that are transparent for banks and tax authorities. Our confidentiality is set out in the contract: we disclose data about you, your family and your assets to the trustee, the bank and the authorities to the extent the procedure requires.
Turnkey trust registration is a chain from the analysis of the family and assets to the trust account and the first report in Ukraine, and one team runs all of it.

If a separate company is needed to hold the assets, we register it within the same project: company registration abroad.
Usually, in our experience, a trust with a partner trustee is set up within a few weeks; a private foundation and the trust's bank account take longer. The timeline depends on the case, its details, the work of the authorities and force majeure.
The notice to the State Tax Service of Ukraine is due within 60 days of the trust's creation, so we put this date in the plan from day one.
We calculate the cost of setting up a trust for each task; it depends on the country, the form and the assets that go into the trust.
We state government fees and the costs of the trustee, notaries and translators in advance as separate lines. We will give you an estimate within a working day after a short description of your task.
A trust connects the trustee, the bank and the tax authorities of several countries, and clients entrust it to us for five reasons.
For fourteen years we have set up structures, opened accounts and handled taxes in 50+ jurisdictions. We know the requirements of registrars, banks and tax authorities from our own cases.
Correspondence with the trust company, the register and the bank and replies to their requests are on us. From you we need documents and decisions.
We rework remarks from the trustee, the register and the bank at no extra charge. Trust services are provided by licensed partners in the country, and responsibility towards you is ours.
The trust, the company, the account, accounting and taxes, including Ukrainian CFC rules, in one pair of hands, with no need to look for separate contractors.
The scope of work, timelines and confidentiality are set out in the contract. We disclose data about you, your family and your assets to the extent the procedure requires.
Setting up a trust goes step by step: goals and form first, then the trustee and documents, then the assets, the account and Ukrainian reporting.
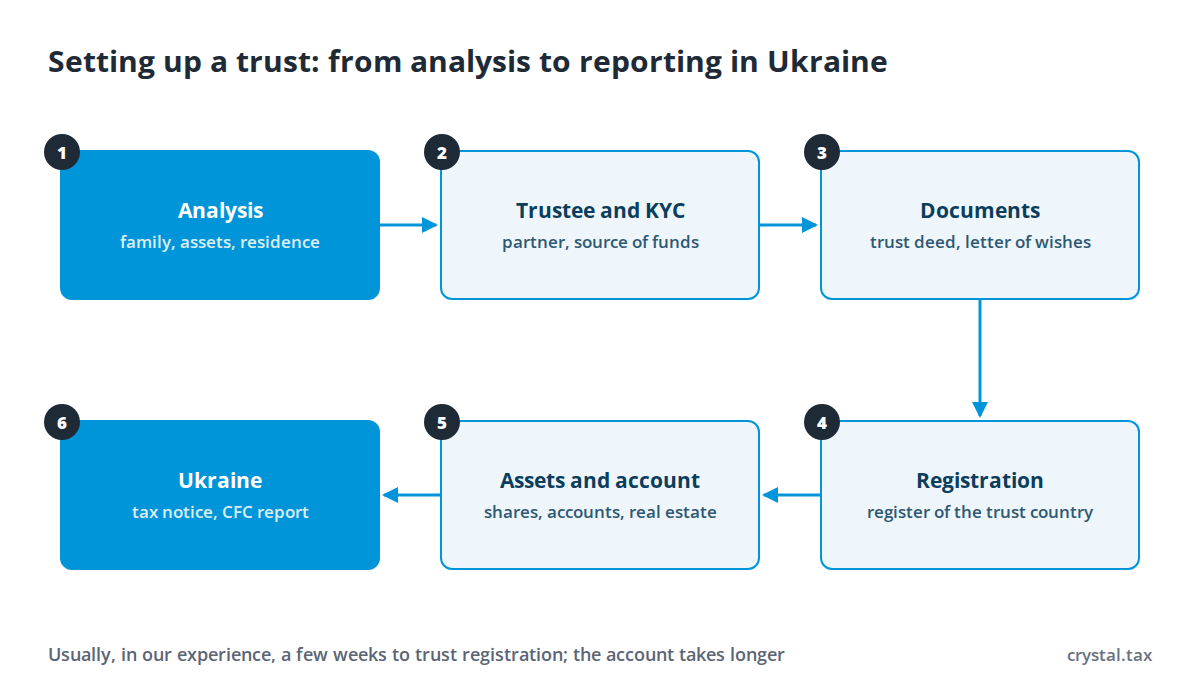
For trust registration, the trustee and the bank check the settlor, the beneficiaries and the origin of the assets; the exact list depends on the country and the trust company.
We translate documents in Ukrainian, tell you where an apostille and a notarised copy are needed, and check the package before it goes to the trustee.
A trust and a private foundation serve the same purposes, managing family capital and passing it to the next generations, but they are built differently.
| Feature | Trust | Private foundation |
|---|---|---|
| Legal nature | A legal relationship without a legal entity; the assets belong to the trustee | A legal entity; the assets belong to the foundation itself |
| Main document | Trust deed, with a letter of wishes | Charter, by-laws, regulations |
| Who manages | The trustee, often overseen by a protector | The foundation council |
| Legal tradition | Common law: England and Wales, Cyprus, Singapore | Civil law: Liechtenstein and other countries |
| For Ukrainian tax purposes | An entity without legal personality that may be treated as a CFC | A foreign legal entity or an entity without legal personality, depending on the law of the country of registration |
Describe your family, assets and the purpose of the trust, and within a working day we will propose the form, the country and the work plan. The first 10-minute call is free.
Tax Code of Ukraine (as amended 17.09.2026): art. 39-2, 120.7, 167, 170.11-1, para. 72 of subsection 10 of section XX; Civil Code of Ukraine: § 8 of chapter 49, art. 597-1 et seq.; chapter 70, art. 1029; GOV.UK: Check if you need to register a trust; HMRC Trust Registration Service Manual: TRSM60020; CySEC: Cyprus Trusts Beneficial Owners Registry (CyTBOR); CyLaw: Cyprus International Trusts Law 69(I)/1992; Lilex: PGR, Art. 552 § 19–20; MAS: Trust Companies Act; Court of Justice of the EU: press release 188/22 on cases C-37/20 and C-601/20; OECD: CRS MCAA signatories and first exchange dates. Checked: 27.09.2026.
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
“Crystal Tax provided invaluable assistance in setting up our company in the United Arab Emirates…”
Yevelina K.2 years ago · Google Maps
“Opening a bank account abroad sounded scary at first, but Crystal Tax made it super easy. They knew exactly which banks to approach, what paperwork was needed…”
Sergei M.a year ago · Google Maps
“As a fast-growing startup, we needed clear, actionable tax advice — and Crystal Tax delivered exactly that. No jargon, no fluff.”
Inna M.a year ago · Google Maps
Briefly describe your task: the country, the business activity and the timing. That is enough for us to propose a solution and the order of work.
We reply within one business day.
Or message us
 Telegram
 WhatsApp