
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
Turnkey LLC accounting services for foreign-owned LLCs and corporations in the US: bookkeeping, federal and state filings, catch-up for missed years and the Ukrainian CFC report for owners resident in Ukraine.
Since 2012 · 50+ jurisdictions · Form 5472, 1120, 1065 · US books and CFC report by one team
In brief
Pick the situation closest to yours: a short outline of the route and the first step.
Yes: for a foreign-owned LLC both the owner's contribution and the owner paying company expenses are reportable. We review the statements, prepare Form 5472 with a pro forma 1120 and pay the state tax.
Example. An owner from Kyiv formed an LLC in Wyoming, put his own money into the account and paid for the registered agent and a website. There were no sales that year, yet the contribution and the expenses paid by the owner made Form 5472 mandatory.
Discuss this case →We rebuild the books from the statements, prepare the missing forms for every year and file them as one package. If an IRS penalty letter has arrived, we prepare a reply explaining the reasons.
Example. A Delaware company ran for three years without returns, and the owner found out when the bank asked for tax documents. The years were rebuilt and the package went to the IRS in a single mailing.
Discuss this case →A two-member LLC is treated as a partnership by default and files Form 1065 with Schedule K-1. We check whether there is income connected with a US business and whether withholding for foreign partners applies.
Example. Two co-owners of an IT studio were paid by American clients through an LLC. We sorted out which income relates to US activity and prepared a 1065 with a K-1 for each of them.
Discuss this case →We keep the books, prepare Form 1120, calculate Delaware franchise tax under the method that gives the lower amount and file the state annual report by 1 March.
Example. A startup with a Delaware corporation received a large franchise tax bill based on the number of shares. Recalculated under the assumed par value capital method, the amount dropped many times over.
Discuss this case →We prepare the financial statements of the LLC or corporation in a form suitable for the Ukrainian CFC report and help the owner calculate the adjusted profit.
Example. An LLC owner resident in Ukraine received a CFC query from his bank. We compiled the company's statements for the year and prepared the data for his tax return.
Discuss this case →We prepare the final federal returns and close out state taxes and registration, so that no charges arrive after dissolution.
Example. The owner had stopped using his LLC, yet the state kept charging tax. We filed the final forms and the termination documents, and the charges stopped.
Discuss this case →Turnkey LLC accounting services cover everything a company must keep and file at the federal level and in its state of formation. If you do not have a company yet, start with US company registration: the books are easier to set up from day one.

For companies with regular transactions we keep the books monthly or quarterly, so the year-end close comes down to reconciliation and preparing the forms. For small LLCs with occasional payments an annual review of the statements early in the year is enough. Either way you receive a deadline calendar, and we handle questions from banks, clients and the tax authorities as part of routine work.
Payroll, multi-state activity and catch-up for prior years are assessed separately if they apply to your business. The scope is fixed in the contract before we start.
The key US tax filing dates for a non-resident LLC on a calendar year are 15 March for partnerships, 15 April for corporations and single-member LLCs with a foreign owner, and 1 June for the Delaware LLC tax.
Form 7004 usually extends the federal filing deadline by six months, while the tax payment deadline stays the same. We file the extension before the original due date.
Usually, in our experience, the annual package for an LLC without employees is ready in 2–4 weeks after we receive the statements, and for a corporation with active operations in 4–6 weeks. Catching up several missed years takes 1–2 months. Timing depends on the case, its details, the authorities and force majeure. IRS response and processing times are outside these estimates.
The IRS accepts Form 5472 with a pro forma 1120 by fax or by mail, and there is no electronic acknowledgement for it. We therefore keep the fax transmission confirmation or the mail tracking record as proof of timely filing in case of a penalty dispute. For corporate and partnership returns filed electronically, we keep the acceptance confirmation. IRS letters about filed forms may arrive several months later, and we reply to them as part of our service.
If the deadline is close, send us the statements for the year. Within a working day we will tell you whether we can make the date or should file an extension first.
We price LLC accounting services for each specific company: the fee depends on the volume of transactions and the set of filings.
Our proposal lists ongoing bookkeeping, annual filings and catch-up for prior periods as separate lines, so you can see what you are paying for. Government fees and state taxes are paid separately against the authorities' invoices; we calculate them and make sure they are paid.
Describe the task briefly: entity type, state, year of formation, number of owners, approximate transaction volume and the last closed period. We will give an estimate within a working day. For a complex structure it is easier to start with a consultation: 30 minutes, 100 euros; a 10-minute intro call is free.
Accounting for a foreign-owned US company depends on details: which transactions are reportable, which state and which deadline apply, and how the Ukrainian tax authority will read it.
Fourteen years of work with companies in 50+ jurisdictions. We know the requirements of the IRS, the states, banks and the Ukrainian tax authority from our own cases.
Correspondence with the IRS and the state and replies to bank queries about the financial statements are on us. You provide documents and decisions.
If the IRS, the state or a bank returns documents with remarks, we rework them at no extra charge.
The company, the account, the books, US taxes and the CFC report in Ukraine are handled by one team, so there is no need to look for separate contractors.
Scope, timing and liability are fixed in the contract, and it includes a confidentiality clause.
Accounting for a foreign-owned LLC starts with a review of the company and its statements and ends with filed returns and next year's calendar.
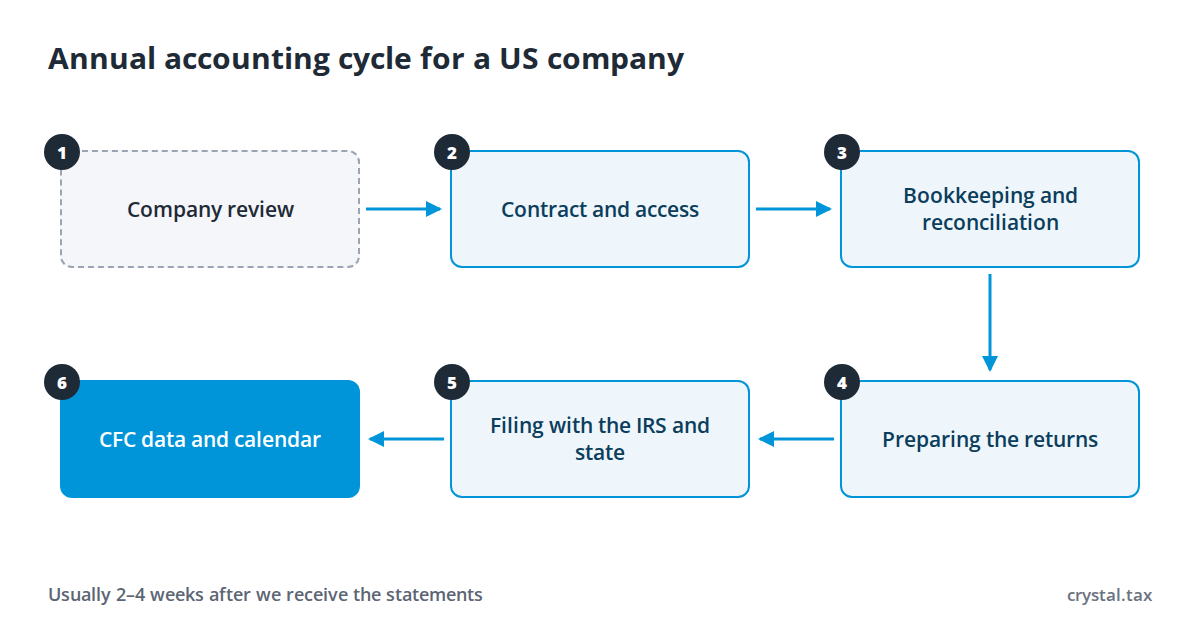
US tax filing for a non-resident LLC requires the formation documents, the EIN and complete statements for all accounts for the period.
A non-resident without an SSN or ITIN obtains an EIN through Form SS-4 by phone, fax or mail, as the online application is unavailable to them. An ITIN is usually unnecessary for the company's filings; it is needed if the owner files a personal US tax return.
You send statements and documents electronically through a secure channel, and read-only access to the bank and payment systems is enough. Paper originals are usually unnecessary for the filings. IRS letters go to the company's US address, so the registered agent or mail service must forward scans without delay: IRS notices set a response deadline.
We agree the exact list after the initial review. If translations of Ukrainian documents are needed, we arrange them ourselves.
The set of federal filings depends on the entity type and tax classification of the company.
| Company | Main form | Deadline for a calendar year | Tax at company level |
|---|---|---|---|
| Single-member LLC with a foreign owner | Form 5472 with a pro forma Form 1120 | 15 April | None, income belongs to the owner |
| Multi-member LLC | Form 1065, Schedule K-1 | 15 March | None, withholding for foreign partners on Forms 8804 and 8805 may apply |
| C-Corp or LLC that elected corporate taxation | Form 1120, plus Form 5472 where a foreign owner holds 25 percent or more | 15 April | Federal rate of 21 percent |
A Form 7004 extension gives six more months to file. A single-member LLC with a foreign owner cannot e-file Form 5472: it goes only by fax or mail to a dedicated IRS unit.
A corporation in which a foreign person owns 25 percent or more of the shares also attaches Form 5472 to its Form 1120 for each related foreign party it had transactions with. Besides the federal forms, a company may have income or gross receipts tax returns in the states where it operates. In Delaware and Wyoming, a company with no activity in the state mainly deals with the annual tax, franchise tax and annual report, while employees, a warehouse or an office in another state widen the set of filings. That is why the initial review records where the company's clients, employees and property are.
| State | LLC | Corporation |
|---|---|---|
| Delaware | Annual tax 400 USD by 1 June, no annual report is filed | Annual report and franchise tax by 1 March; minimum 175 USD under the authorized shares method or 400 USD under the assumed par value capital method, plus the report filing fee |
| Wyoming | Annual report by the first day of the anniversary month, license tax from 60 USD | Same rules as for an LLC |
Late payment in Delaware incurs a 200 USD penalty and interest of 1.5 percent per month. In Wyoming a company is administratively dissolved if the report is not filed within 60 days after the due date.
Sales tax in the US is set by the states; there is no federal sales tax. A registration obligation arises where the seller has a presence or sales above the state threshold; state rules for digital services differ, so we check each case separately.
Form 5472. The penalty for failure to file is 25,000 USD. If the form is still not filed 90 days after an IRS notice, another 25,000 USD is added for each 30 days.
BOI. Since 2025, companies created in the US have been exempt from beneficial ownership reporting to FinCEN; the final rule of 11 August 2026 confirmed this exemption. Only foreign companies registered to do business in a US state file the report.
Form 1099-NEC. For payments to US non-employee contractors for 2026 and later years, the reporting threshold is 2,000 USD per year per recipient.
Withholding on payments to foreign persons. If a US company pays foreign persons US-source income, such as interest, royalties or dividends, it may have to withhold tax and file Form 1042-S. For LLCs with foreign partners we separately check section 1446 withholding on Forms 8804 and 8805. Payment for services performed outside the US usually falls outside these rules, though we verify this against the contracts.
CFC in Ukraine. A Ukrainian tax resident who controls a US LLC or corporation files a controlled foreign company report together with the annual tax return and attaches the company's financial statements. For this, the US books must produce annual financial statements that can be attached to the report. We handle similar tasks for other countries under our international company accounting service.
A zero return for a US LLC is zero only on paper: the return is filed even with no revenue, and transactions with the owner are reported in it.
For a single-member LLC with a foreign owner, reportable transactions include money contributed to the account, company expenses paid by the owner, loans between the company and the owner, distributions to the owner, and amounts related to forming and dissolving the company. So we start with the statements: even a single transfer from the owner makes Form 5472 mandatory. The state tax is payable regardless of activity.
Catch-up goes year by year, starting from the earliest. We collect the statements, rebuild the books, prepare the forms for each year and file them as a package with a cover letter. The IRS may assess a failure-to-file penalty, so the package includes an explanation of the reasons for the delay; the decision on the penalty rests with the IRS. State arrears are settled separately to restore the company's good standing status, which banks often request.
Before dissolution we close the books as of the date operations cease, prepare final federal forms marked as final return, pay off state taxes and file the termination documents in the state of formation. If the bank account is still open, we agree how to close it and pay the balance to the owner; that payment also goes into the final Form 5472.
When a second member joins an LLC, the company by default moves from disregarded entity status to a partnership, and the whole set of filings changes from the next period. An election to be taxed as a corporation on Form 8832 also changes the forms and the tax: the company becomes subject to its own income tax at 21 percent. Such changes are best agreed with us in advance, before the transaction.
Send us the entity type, state, year of formation and last closed period: within a working day we will reply with the filings you need and how long they will take. If you prefer to talk, we can start with a free 10-minute call.
IRS: Instructions for Form 5472; IRS: Instructions for Form 1120; IRS: Instructions for Form 1065; IRS: Instructions for Forms 1099-MISC and 1099-NEC; IRS: Get an Employer Identification Number; FinCEN: final BOI rule of 11.08.2026; Delaware: LLC, LP, GP tax instructions; Delaware: Annual Report and Tax Information; Wyoming Secretary of State: Business FAQ; Tax Code of Ukraine, Article 39-2. Checked: 27.09.2026.
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
“Crystal Tax provided invaluable assistance in setting up our company in the United Arab Emirates…”
Yevelina K.2 years ago · Google Maps
“Opening a bank account abroad sounded scary at first, but Crystal Tax made it super easy. They knew exactly which banks to approach, what paperwork was needed…”
Sergei M.a year ago · Google Maps
“As a fast-growing startup, we needed clear, actionable tax advice — and Crystal Tax delivered exactly that. No jargon, no fluff.”
Inna M.a year ago · Google Maps
Briefly describe your task: the country, the business activity and the timing. That is enough for us to propose a solution and the order of work.
We reply within one business day.
Or message us
 Telegram
 WhatsApp