
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
Delaware C-Corp for non-US founders, set up end to end for a startup preparing for an accelerator or a venture round: the corporation, founder shares, product IP, EIN and a flip of your existing company from Ukraine or Estonia.
Since 2012 · 50+ jurisdictions · EIN without SSN or ITIN · the founders' Ukrainian side handled by the same team
In brief
Pick the situation closest to yours: a short outline of the route and the first step.
We incorporate with a share class and a number of authorized shares that fit standard investment documents, issue founder shares with vesting and secure the product IP in the company. First step: the list of founders, their stakes and the round timeline.
Example. Two founders from Kyiv and Warsaw get into an accelerator that invests through a SAFE. Before signing, we incorporate the company and assemble the package the accelerator's lawyers request.
Discuss this case →We create the Delaware C-Corp and choose the route: exchanging the TOV stakes for corporation shares, or transferring the code rights and contracts to it. We calculate the Ukrainian taxes, CFC rules and currency side before anything is signed.
Example. A SaaS product has run for several years through a TOV and two developer FOPs. The FOPs assign the code rights under written agreements, and the TOV becomes a subsidiary of the corporation.
Discuss this case →We make the Delaware corporation the parent company: the founders transfer their OÜ shares to it in exchange for stock, and the OÜ keeps operating as a subsidiary. We handle the Estonian part with our partners in Estonia.
Example. A team with e-Residency works through an OÜ for its first EU clients, and a US fund makes the flip a condition for closing the round. We build the structure around the fund's checklist.
Discuss this case →We check which method the tax was calculated under and recalculate it with the Assumed Par Value Capital Method using the balance sheet data from Form 1120. We file the annual report and clear the state balance.
Example. A startup with 10 million authorized shares receives a notice for tens of thousands of dollars under the share count method. With modest assets, recalculating under the second method often brings it down to the minimum.
Discuss this case →We prepare founder stock purchase agreements with vesting, decide which founders need an 83(b) election based on their tax residence, and track the 30-day deadline.
Example. The technical co-founder lives in California, the other two in Ukraine and Germany. For the American we file the 83(b) in the first days after the shares are issued; for the others we work out the taxes in their countries.
Discuss this case →We convert the LLC into a corporation before the round: Delaware law allows converting an LLC into a corporation. We check the tax consequences for the members and turn their interests into shares.
Example. A founder runs sales through an LLC opened by an online formation service. Before the round we convert it into a C-Corp, issue shares and create an option pool.
Discuss this case →A done-for-you Delaware C-Corp is a corporation ready to sign investment documents: formation documents, founder shares, product IP, EIN, a bank and a filing calendar. We fix the exact scope in the contract.

We hand over a calendar: the Delaware annual report and franchise tax by March 1, the federal return, Form 5472, registration in other states if employees or an office appear there, Form D for a round under Regulation D, and the founders' reporting in Ukraine.
A startup raising venture capital usually chooses a Delaware C-Corp; a business without outside investors and with one or a few owners is often fine with an LLC. The difference lies in taxes, in the tools available for the team and in what investors expect.
| Criterion | Delaware C-Corp | Delaware LLC |
|---|---|---|
| Income tax | 21 percent federal tax at the corporate level | None at the company level by default: income passes through to the members |
| Who pays the tax | The corporation, then shareholders on dividends. Non-residents are withheld 30 percent by default, less under the US–Ukraine tax treaty | The members, under the rules of their own country. A foreign-owned single-member LLC with owner transactions files Form 5472 with a pro forma 1120 |
| Shares and options | Share classes, an option pool, SAFEs and preferred stock for the round | Membership interests; options are harder to set up |
| What venture investors expect | The standard for rounds and accelerators | They usually ask for conversion into a corporation before the deal |
| Annual state tax | Franchise tax and annual report by March 1; the amount depends on the calculation method | A flat state tax by June 1 |
| Federal reporting | Form 1120, plus Form 5472 with 25 percent foreign ownership and related-party transactions | Depends on the number of members and the tax classification |
| Best for | Startups raising investment, team options, a future sale of the company | Services, trading, a single-owner holding company |
If you are not planning to raise and prefer profit to be taxed at the owner level, see our Delaware LLC page. If you have not chosen a state yet and need a US company for sales or a bank account, start with US company formation. An LLC that is already operating can later convert into a corporation: section 265 of the General Corporation Law and section 18-216 of the Delaware LLC Act expressly allow it.
Tell us about the product, the founders and your round plans, and on a free 10-minute call we will tell you whether you need a C-Corp or a flip and where to start.
A startup flip means creating a Delaware corporation on top of an existing business, so the investor receives shares in a US parent company while the product, team and revenue sit within its group. In practice this is called a Delaware flip.
A clean cap table with no verbal promises of equity, signed IP assignments from every author of the code, stock purchase agreements with vesting, board consents, filed 83(b) elections, no franchise tax debt and filed IRS returns. We record the founders' arrangements among themselves in a shareholders' agreement, and check the SAFE and round documents against the corporation's charter.
Usually, in our experience, forming a Delaware C-Corp with the founder document package takes 1–2 weeks, the EIN adds 1–4 weeks, and a flip takes 1–3 months. Timing depends on the case, the details, the authorities and force majeure.
| Stage | Usually, in our experience |
|---|---|
| Structure, share count, vesting, document list | 2–5 business days |
| Delaware certificate of incorporation | From a few hours to a few days: the state offers expedited processing within one hour, two hours, the same or the next business day |
| Bylaws, resolutions, founder stock purchase, IP assignment | In parallel with incorporation, signed electronically |
| EIN for a corporation without SSN or ITIN | 1–4 weeks |
| Bank or fintech provider | Set by the bank |
| Flip from a TOV, FOP or OÜ | 1–3 months, longer when changes must be registered in several countries |
The 83(b) deadline is 30 days from the date the shares are issued, so we schedule the founder share issuance to leave time for the filing.
We quote Delaware C-Corp formation case by case: the price depends on the number of founders, whether a flip is needed and the volume of documents for the investor.
Delaware state fees and registered agent services are shown separately in the proposal. We work under a contract. After a short description of your task we assess it within one business day and send a quote with stages and timing.
A Delaware corporation ties together founder stakes, product IP and taxes in several countries, and founders trust us with it for five reasons:
Fourteen years of forming and structuring companies in 50+ jurisdictions. We know the requirements of registries, the IRS, banks and investors' lawyers from our own cases.
The Delaware filing, the EIN application, correspondence with the bank and replies to requests are handled by us together with our US partners. We need the founders' details, decisions and signatures from you.
We resolve comments from the registry, the IRS or the bank at no extra charge under the contract until the agreed stages are complete. Decisions on applications are made by the authorities and the bank.
The US corporation, the flip of a Ukrainian or Estonian company, the code IP assignment, bookkeeping, Form 1120, Form 5472 and the founders' Ukrainian CFC reporting, all in one place.
Scope, timing and confidentiality are set out in the contract. We disclose founder data and round terms only to those who require them by law or procedure.
We form a Delaware C-Corp in six steps. The founders provide data, decisions and signatures; we do the rest.
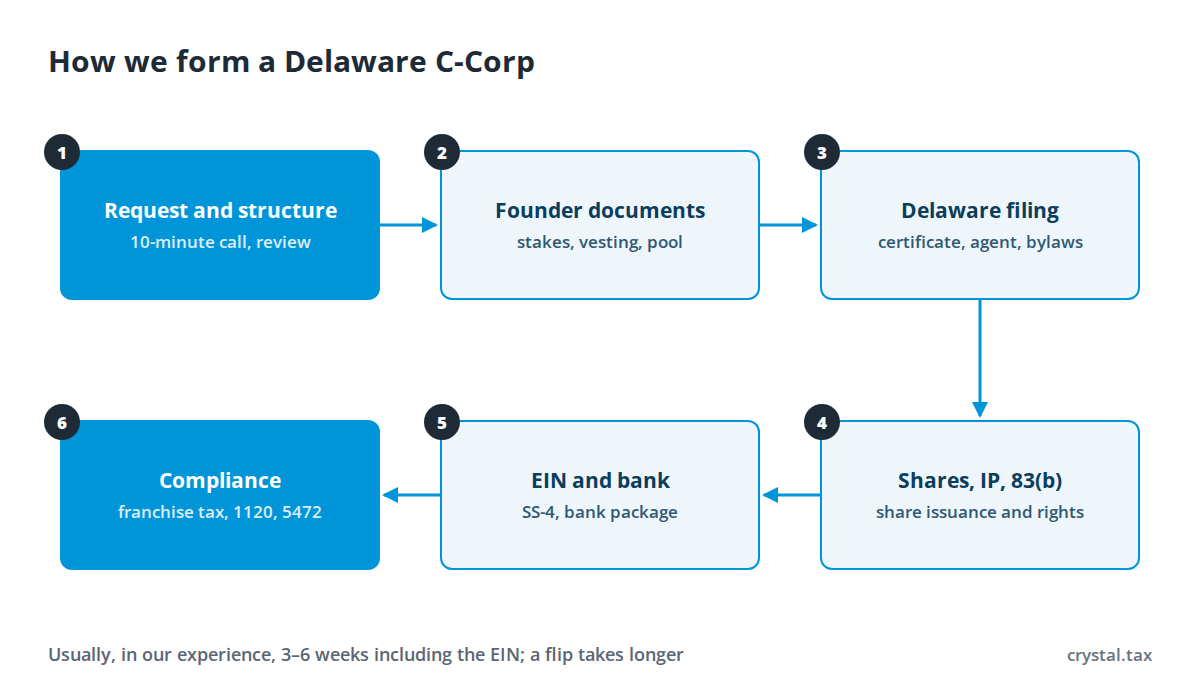
If the founders have not yet agreed on roles and stakes, we start with a strategy session and incorporate based on its results.
To open a Delaware corporation we need the founders' details and a clear view of how they split the company. No trip to the US is required.
We give you the exact list after the first conversation. We arrange translations, apostille and e-signing ourselves.
A Delaware C-Corp reports to the State of Delaware, to the IRS and in the states where it does business, and these obligations apply whether or not it has revenue.
| Obligation | Who | Deadline | Basis |
|---|---|---|---|
| Annual report and franchise tax | Every Delaware corporation. Annual report fee $50, minimum tax $175 or $400, maximum $200,000 | By March 1 for the previous year. Late penalty of $200 plus 1.5 percent per month on the tax and penalty | Division of Corporations |
| Form 1120, 21 percent tax | Every C-Corp | The 15th day of the 4th month after the end of the tax year, April 15 for a calendar year. Extension on Form 7004 | IRS, Instructions for Form 1120 |
| Form 5472 | A corporation in which a foreign shareholder directly or indirectly owns 25 percent of the voting power or value of the shares, if it had related-party transactions | Together with Form 1120. Penalty for failing to file or filing a substantially incomplete form: $25,000 | IRS, Instructions for Form 5472 |
| BOI with FinCEN | Companies created in the US are exempt | The final FinCEN rule was issued on August 11, 2026, published in the Federal Register and took effect on August 14, 2026 | FinCEN |
| Delaware corporate income tax of 8.7 percent | A corporation doing business in Delaware. A corporation with only a registered office in the state is exempt | Under state rules | Delaware Code, title 30, section 1902 |
| Taxes and registration in other states | If employees, an office or sales create nexus with a state | Under state rules | State law |
| Withholding on dividends to foreign persons | A corporation paying dividends | At payment. 30 percent by default, no more than 15 percent under the US–Ukraine treaty, and 5 percent for a company holding at least 10 percent of the votes | IRS, NRA withholding, US–Ukraine tax treaty, Article 10 |
| Form D | A corporation selling shares or SAFEs under Rule 506 of Regulation D | Within 15 days after the first sale | SEC |
Form 5472 with a pro forma 1120 for a foreign-owned single-member LLC is a separate rule for LLCs; a corporation attaches Form 5472 to its own Form 1120.
The franchise tax of a Delaware corporation is calculated under two methods, and the company may pay under whichever gives the lower amount. The state notice goes to the registered agent in December and is calculated under the share count method.
A corporation has 10,000,000 authorized shares with a par value of $0.00001, 8,000,000 shares issued and Schedule L assets of $50,000. Under the share count method: 250 plus 999 times 85, a total of $85,165. Under the second method: assumed par of $0.006250, capital of $62,500, a calculated tax of $25, so the minimum of $400 is paid. Plus $50 for the annual report.
If the number of shares or the par value changed during the year, the tax is split into periods prorated by days. The second method needs finished financial statements, so we handle the bookkeeping and the annual report together.
A founder who is a Ukrainian tax resident must report the Delaware corporation in their Ukrainian filings if it becomes their controlled foreign company.
The report and notices are prepared by Crystal Tax accountants: Ukrainian CFC reporting.
Describe in a few lines the product, the founders and the countries they live in, where the company operates now and your plans for investors. Within one business day we will propose a route: a new corporation or a flip, founder documents, timing and an estimate. The first 10-minute call is free; a detailed 30-minute consultation costs €100.
Delaware Division of Corporations: Annual Report and Tax Information; Delaware Division of Corporations: How to calculate franchise taxes; Delaware General Corporation Law, sections 101 and 102; Delaware General Corporation Law, section 132; Delaware Code, title 30, section 1902; IRS: Instructions for Form 1120; IRS: Instructions for Form 5472; IRS: Form 15620, Section 83(b) Election; IRS: Instructions for Form SS-4; FinCEN: Beneficial Ownership Information Reporting; SEC: Filing a Form D notice; Tax Code of Ukraine (Podatkovyi kodeks Ukrainy), Article 39-2. Reviewed and updated on 27.09.2026.
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
“Crystal Tax provided invaluable assistance in setting up our company in the United Arab Emirates…”
Yevelina K.2 years ago · Google Maps
“Opening a bank account abroad sounded scary at first, but Crystal Tax made it super easy. They knew exactly which banks to approach, what paperwork was needed…”
Sergei M.a year ago · Google Maps
“As a fast-growing startup, we needed clear, actionable tax advice — and Crystal Tax delivered exactly that. No jargon, no fluff.”
Inna M.a year ago · Google Maps
Briefly describe your task: the country, the business activity and the timing. That is enough for us to propose a solution and the order of work.
We reply within one business day.
Or message us
 Telegram
 WhatsApp