
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
Where to incorporate a startup is the first decision we make with you. Then we form the company turnkey, lock in founder equity and IP rights, and prepare the first contracts.
Since 2012 · 50+ jurisdictions · company, equity, IP and contracts in one team · first 10 minutes free
In brief
Pick the situation closest to yours for a short route and the first step.
We compare a Delaware C-Corp with other forms from a fund's point of view, incorporate the corporation, obtain the EIN and set up the option pool and founder vesting from day one. Code rights move to the company before the first investor talks.
Example. Two founders of a SaaS product from Kyiv are preparing for a US accelerator. We incorporate in Delaware, issue founder shares with vesting and assign the code from the founders to the company.
Discuss this case →We compare Estonia, Ireland, Poland and Cyprus on tax, director requirements and banking. We calculate the founders' taxes in Ukraine, including the Ukrainian CFC rules.
Example. A logistics startup sells subscriptions to companies in Germany and the Netherlands. We register an EU company, prepare contracts with developers in Ukraine and set up CFC reporting.
Discuss this case →We check where a non-resident director works without extra conditions. In Estonia the company is run online through e-Residency with a legal address or contact person, and Ireland requires an EEA-resident director or an insurance bond. We choose the option that will pass the bank's review.
Example. Founders based in the UAE and Georgia are launching a service for European clinics. We form an Estonian company, arrange the legal address and contact person and prepare the bank package.
Discuss this case →We show in numbers what happens to such a company under the Ukrainian CFC rules, at the bank and in investor due diligence. We suggest a jurisdiction that funds and banks accept without long explanations.
Example. The founder of a mobile app plans to open a company in the BVI. We calculate the CFC position, check the future investor's requirements and compare it with a Delaware corporation.
Discuss this case →We record the equity in a cap table, set vesting and cliff, good leaver and bad leaver exit terms, voting and share transfer rules. Everything goes into the shareholders agreement and the articles of association.
Example. Three founders of an EdTech project split equity equally, while one of them works only half-time. We agree four-year vesting and the terms on which he can leave.
Discuss this case →We prepare a developer agreement that transfers the economic rights to the code to the company, plus an NDA and acceptance rules. If the code already exists, we draft a separate IP assignment.
Example. A contractor built the prototype of a fintech service on a verbal arrangement. We assign the rights to the existing code and sign an agreement for further development.
Discuss this case →Turnkey startup incorporation abroad covers the choice of country and company form, the registration itself, the documents on equity and code rights, and the first contracts. Founders provide decisions and documents, and we handle the correspondence with registries, tax offices and banks.

The best country to register a startup depends on three questions: who will invest, where the clients are and where the team lives. Corporate tax matters, yet for a startup with no profit in the first years the investor's and the bank's requirements come first.
A fit if you plan to raise from a US fund, join an accelerator or sell to US clients. In practice, funds usually invest in a Delaware corporation (C-Corp): it is formed by filing a certificate of incorporation with the Division of Corporations. The federal corporate income tax is 21 percent, and state taxes are separate. A Delaware corporation files its annual report and pays franchise tax (the annual state tax on Delaware companies) by March 1. A founder without a US SSN obtains an EIN on Form SS-4, and a corporation that is at least 25 percent foreign-owned files Form 5472 (the IRS information return on related-party transactions) for each year with related-party transactions. Since March 2025, companies formed in the US are exempt from beneficial ownership reporting to FinCEN, and in August 2026 FinCEN confirmed this in a final rule. Details on the page company formation in the USA.
A fit for a team that sells in the EU and works remotely. An OÜ is registered and managed online through e-Residency (Estonia's digital residency) with a digital signature. The company needs a legal address in Estonia or a contact person, and licensed providers offer this service. Corporate tax in 2026 is 22/78 and arises on profit distribution, so reinvested profit is untaxed. Details: company in Estonia.
A fit for products aimed at the EU and UK markets that want English law and English-language documents. Tax on trading profit is 12.5 percent, and on non-trading income, such as passive income, 25 percent. Under the general rule of the Companies Act 2014, at least one director must be resident in the EEA, or the company holds an insurance bond. Details: company formation in Ireland.
A fit if the founders relocate to the UAE or sell in the Gulf region. Corporate tax is 0 percent up to AED 375,000 and 9 percent above that amount. A free zone company with Qualifying Free Zone Person status (the UAE status that gives 0 percent on qualifying income) pays 0 percent on qualifying income if it has real presence in the country. Small businesses with revenue up to AED 3 million can apply Small Business Relief for tax periods ending no later than December 31, 2029. Details: company formation in the UAE.
A fit when you need a European holding company, an English-style corporate law model and a preferential regime for IP income (IP box, a reduced tax regime for income from intellectual property) under OECD rules. From January 1, 2026, the corporate tax rate in Cyprus is 15 percent, up from 12.5 until the end of 2025. Details: company in Cyprus.
Other countries: the UK and Poland suit their own markets and teams. We cover them and other countries on the page company formation abroad.
Tell us about the product, the founders and your investment plans, and on a free 10-minute call we will say where to incorporate and where to start.
Founder equity, the company's rights to its code and developer contracts are the first things an investor checks in due diligence (the investor's legal and financial review), so we put them in place together with the registration. Fixing these documents before a deal takes longer and costs more than signing them at the start.
A cap table (capitalisation table) lists everyone who holds shares or options in the company and their percentages. It shows the founders' stakes, the reserve of options for the team (option pool) and how the stakes will change after investment.
Vesting is the arrangement under which a founder earns their stake gradually, for example over four years. The cliff is the first period, usually one year, before which no part of the stake vests. Good leaver and bad leaver terms set how much of the stake a departing founder keeps and at what price the company or partners buy it back. Together with voting, non-compete and the rules for selling the company, these terms go into the shareholders agreement.
An IP assignment is a document by which a founder or developer transfers to the company the economic rights to code, design, databases and brand. Without such a document, the rights may stay with the author, and the investor will see this during due diligence. We assign rights to work already created and add an IP clause to contracts for future work. We register the trademark in the company's name.
With a developer or contractor we sign an agreement that sets out tasks, acceptance, payment, transfer of rights to the result and confidentiality. An NDA (non-disclosure agreement) covers employees, contractors and partners with whom you discuss the product. For each country we follow its rules on rights to work results.
We prepare these documents together with the shareholders agreement and the contracts listed above, and continue as legal support for startups: new investors, stock options, document changes.
This page is for a product startup: a founding team, your own product, plans to raise investment and code rights that must belong to the company. The focus here is the country for your investor, equity and documents for due diligence.
If you work on client projects, in outsourcing or outstaffing, and are choosing between a Ukrainian FOP (sole proprietor), a Ukrainian TOV (LLC) and a foreign company for your clients, see the page IT company registration for outsourcing and IT services. It covers the forms and taxes of a service IT company.
Usually, in our experience, incorporating a startup abroad takes 1 to 6 weeks depending on the country, and a full launch with a bank account and tax numbers takes 3 weeks to 3 months. Timing depends on the case, its details, the authorities and force majeure.
The registry's official timeline covers only the review of ready documents. If you have an external date, such as an accelerator demo day or signing a term sheet, tell us right away and we will plan the steps around it.
We price startup incorporation abroad per project: the cost depends on the country, the number of founders and the scope of documents for investors.
The only published price is the 30-minute consultation for €100, and the 10-minute intro call is free. We quote a project within one business day after a short description of the task. Comments from the registry or tax office and bank questions about our work are handled at no extra charge. We work under a written contract.
A startup's company has to pass the review of the bank, the tax office and the investor, and founders trust it to us for five reasons:
For fourteen years we have been forming companies, opening accounts and handling tax matters in 50+ jurisdictions. We know the requirements of registries, banks and tax offices from our own cases.
Crystal Tax lawyers and accountants, together with partners in each country, handle correspondence with registries, tax offices and banks and answer their requests. Founders provide documents and decisions.
Comments from the registry or tax office and bank questions about our work are handled at no extra charge.
Company, equity, shareholders agreement, code rights, contracts, bank account, bookkeeping and Ukrainian CFC reporting sit with one team, so you do not need to look for separate contractors.
Scope, timing and confidentiality are set out in the contract. We disclose data about the product, founders and equity only to the extent the procedure requires.
Startup incorporation goes through six steps, from the intro call to reporting. We make the first decisions together, and then we handle the documents and correspondence.
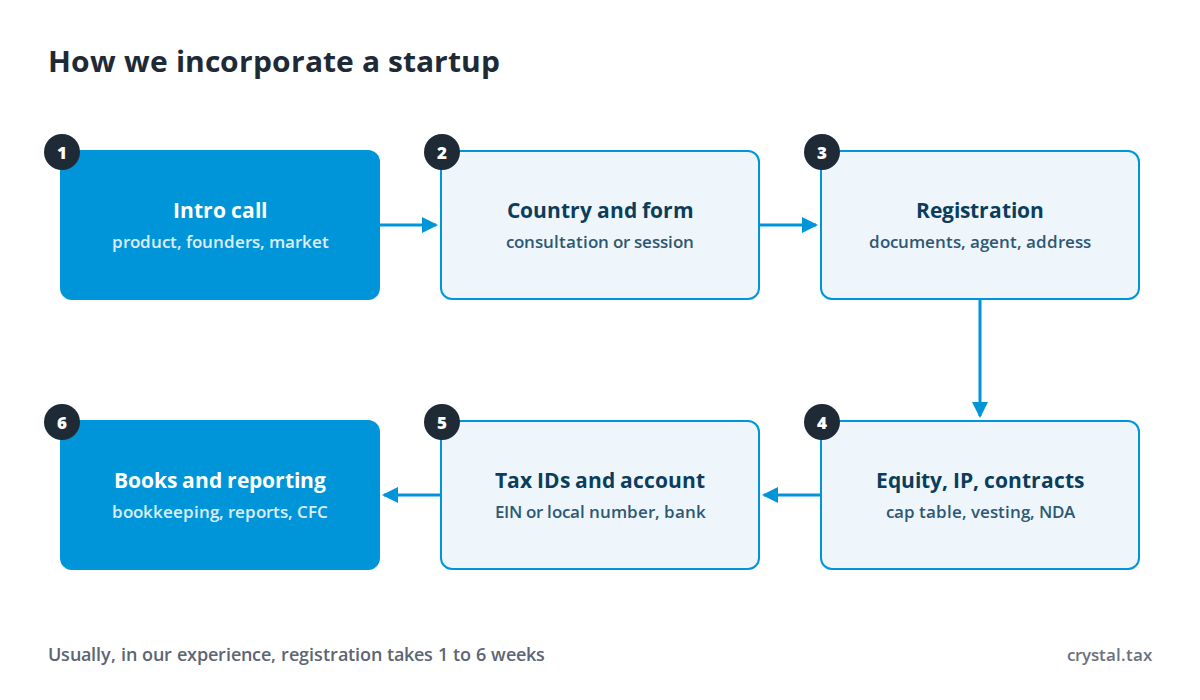
To incorporate a startup you need the founders' documents and a short project description, and the exact list depends on the country.
We send the list for your country after the intro call. We take care of translations and certifications if the registry requires them.
The table shows the basic terms as of September 2026, and we choose for your project taking into account the founders' taxes and the Ukrainian CFC rules.
| Country | Form | Corporate tax | Remote registration and management | Best for |
|---|---|---|---|---|
| US, Delaware | C-Corp or LLC | Federal 21 percent for a corporation, state taxes separate | Yes, EIN for a foreign founder on Form SS-4 | Startups targeting US investors and the US market |
| Estonia | OÜ | 22/78 on profit distribution | Yes, through e-Residency, a legal address or contact person is required | Remote teams with clients in the EU |
| Ireland | Private company limited by shares | 12.5 percent on trading profit, 25 on non-trading income | Yes, with an EEA-resident director or a 25,000 euro bond | Products for the EU with English-language documents |
| UAE | Free zone or mainland company | 0 percent up to AED 375,000, 9 above, 0 for qualifying free zone income | Depends on the free zone, the visa and Emirates ID are issued in the country | Founders who live or sell in the region |
| Cyprus | Private limited company | 15 percent from January 1, 2026 | Through partners in Cyprus | Holding companies and companies with IP income |
A zero-tax jurisdiction such as the BVI, Belize or the Seychelles rarely suits a startup that plans to raise investment: questions come from the Ukrainian tax authority, from banks and from funds.
If you already have an island company, we will work out what to do with it: keep it, redomicile it or close it after the business moves.
A founder who is a Ukrainian tax resident is liable under the CFC rules of Article 39-2 of the Tax Code of Ukraine for every foreign company they control.
We prepare CFC notifications and reports ourselves as part of the company's accounting support.
Describe in two or three sentences the product, how many founders there are and where they live, where your market is and whether you plan to raise investment. Within one business day we will tell you which countries fit and quote the work. The first 10 minutes of the intro call are free. For one specific question, a 30-minute consultation for €100 is the right format.
IRS: Instructions for Form SS-4; IRS: Instructions for Form 5472; IRS: Instructions for Form 1120; FinCEN: Beneficial Ownership Information Reporting; Delaware Division of Corporations: Annual Report and Tax Information; Estonian Tax and Customs Board: tax rates; e-Residency: Start a company; Revenue Ireland: Corporation Tax, basis of charge; Companies Act 2014, section 137; UAE Ministry of Finance: Federal Decree-Law No. 47 of 2022, Corporate Tax; UAE Ministry of Finance: Small Business Relief extended to 31.12.2029; Tax Code of Ukraine, Articles 14.1.213, 39-2, 167, as amended on 17.09.2026; Cabinet of Ministers of Ukraine Resolution No. 1045 of 27.12.2017, list of states; European Commission: EU list of non-cooperative jurisdictions, 17.02.2026; CyLaw: Cyprus Income Tax Law 118(I)/2002, consolidated text. Content checked and updated on 27.09.2026.
Maksym Stepanenko
Managing Partner, Crystal Tax
International client projects since 2012: company structures, tax, immigration, DUNS and NCAGE. 50+ jurisdictions.
“Crystal Tax provided invaluable assistance in setting up our company in the United Arab Emirates…”
Yevelina K.2 years ago · Google Maps
“Opening a bank account abroad sounded scary at first, but Crystal Tax made it super easy. They knew exactly which banks to approach, what paperwork was needed…”
Sergei M.a year ago · Google Maps
“As a fast-growing startup, we needed clear, actionable tax advice — and Crystal Tax delivered exactly that. No jargon, no fluff.”
Inna M.a year ago · Google Maps
Briefly describe your task: the country, the business activity and the timing. That is enough for us to propose a solution and the order of work.
We reply within one business day.
Or message us
 Telegram
 WhatsApp